AIA: Fed Likely to Hold Steady as Design Billings Soften
Key Highlights
- Inflation remains high with no immediate relief, pressuring the Fed to maintain or raise interest rates;
- Construction spending showed a modest increase in August, but inflation-adjusted data indicates a downward trend over the past year;
- Employment in architecture and related fields grew slightly in September, but overall economic momentum is slowing;
- Architecture firms report weak business conditions with declining project inquiries and billings, and a cautious outlook for the coming quarter amid economic uncertainties;
- AI adoption is growing, with nearly half of firms engaging in some capacity; larger firms are more proactive, but formal training remains limited, impacting productivity and strategic growth.
By RICHARD BRANCH, Chief Economist, American Institute of Architects
The first five paragraphs below first appeared October 5 on LinkedIn...
A few economic releases from last week are worth watching — especially for what they may mean for construction and architecture.
Inflation: The Fed’s preferred inflation measure moved up 0.3% in August and was 3.4% higher than a year ago. Core PCE (excluding food and energy) increased 0.2% for the month and 3.0% over the past year. So, no real relief from inflation in August – which isn’t surprising. Does this, in and of itself, change anything for the Fed? No, not in the least. The Fed will be under continued pressure to keep rates where they are, or even raise them, to see any meaningful improvement. That will keep construction financing difficult.
Construction Spending Put in Place: The August numbers were more encouraging. Total construction spending increased 0.9% from July, including a 1.0% increase in private nonresidential spending. But let’s look at this through a different lens. The chart here is nonresidential spending but controlled for inflation. Spending has been trending downward consistently for about a year. But August reversed direction. One month does not a trend make. Sustaining that turn, though, will be difficult as prices keep rising and rates remain high. Still, after a year of steady deterioration, these days a positive is a positive.
Jobs: The September employment report reminded us that the broader economy is losing momentum. Employers added just 29,000 jobs, while the unemployment rate was 4.2%. July and August were also revised down by a combined 60,000 jobs. The news was a little better for our industry. Construction added 11,000 jobs in September, while employment in architectural, engineering, and related services increased by 5,800.
You know how I said “in and of itself” in the commentary on inflation?
I think this weak employment read argues for the Fed holding in October. Core inflation is still high, but not getting worse, and the labor market is clearly slowing. That puts the Fed in a sticky wicket, which I think means they’ll wait for more data before raising further.
____________
Meanwhile, in a September 23rd press release...
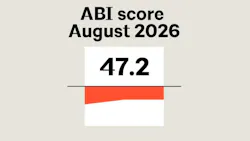
AIA announced that the AIA/Deltek Architecture Billings Index® (ABI) score for August was 47.2. While slightly fewer firms reported a decline in billings in August than in July, the majority of firms continued to see weak business conditions. In addition, inquiries into new projects showed only modest growth this month, while the value of newly signed design contracts continued to decline.
And sentiment about future billings has weakened at architecture firms as well. When AIA first asked this new question at the end of the first quarter, 31% of responding firm leaders indicated that they expected billings to increase in the second quarter. That basically held steady at 30% when asked about the third quarter, but has now fallen to 25% when asked about expectations for the fourth quarter.
Additionally, the share of responding firm leaders who expect billings to decline in the coming quarter has increased from 21% at the end of the first quarter to 29% at the end of the third quarter.
Economic crosswinds intensify
Conditions in the broader economy remained mixed in August. Non-farm payroll employment grew more significantly than had been anticipated, adding 162,000 new jobs in August. Architectural services employment increased as well, adding 700 new positions in July (the most current data available).
Despite this employment growth, inflation ticked back up in August, with the Consumer Price Index (CPI) increasing by 0.4% from July, after rising just 0.1% the previous month. It remains up by 3.4% from one year ago, with recent increases in gasoline and energy prices among the largest contributors. Gasoline prices increased by 3.9% in August and are up by a whopping 27.4% from one year ago.
As a result of higher inflation and healthier-than-expected employment, the Federal Reserve chose to raise interest rates by a quarter point at its September meeting. This is their first rate increase in three years, and their hope is that this will finally start to bring inflation down to their target rate of 2%.
AI adoption gains momentum
September’s special practice questions asked design firm leaders about their adoption of, and investment in, AI technology. Overall, nearly half of responding firm leaders (48%) indicated that they are currently engaging with AI at their firm, with 18% reporting that it is a strategic priority and 30% reporting that their firm is actively using AI and modeling the behavior.
An additional 34% reported that their firm’s current approach to AI adoption is interested but reactive, while 15% said that their approach is currently passive/cautious. Large firms with annual billings of more than $5 million were significantly more likely than smaller firms to report actively engaging with AI, with 30% indicating that it is a strategic priority at their firm.
Despite this, most firms are not currently providing AI training to their staff. Just 7% of responding firms overall have a formal AI training program, while 26% provide AI training by individual demand. While formal programs are relatively uncommon even at large firms (just 12% have one), large firms are much more likely to provide AI training by individual demand, with 43% currently offering it.
At firms that are currently using AI, slightly more than one in five (22%) report that it has substantially increased their firm’s productivity so far. Just 2% indicate that it has decreased their productivity, while the remaining 76% say that productivity has remained about the same. In addition, just 15% of responding firm leaders reported having a budget allocated specifically for AI this year, while 47% indicated that they do not have a dedicated budget, but instead purchase AI/emerging technologies from other budget lines, and the remaining 38% reported that they do not invest currently in AI/emerging technology.
Large firms with an annual budget of more than $5 million were significantly more likely to report having a dedicated budget for AI, with 30% having one, in contrast to 1% of small firms with annual budgets of less than $1 million, and 9% of firms with annual budgets of $1 to $5 million.
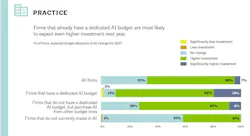
And overall, two-thirds of firms expect to make a higher investment in AI in 2027, which increases to 84% of firms that already have a dedicated AI budget and 75% of firms that purchase AI/emerging technologies from other budget lines, in contrast to 41% of firms that do not currently invest in AI/emerging technology.